Polymarket faces scrutiny over more than $600 million in election trades
A WIRED investigation found repeated trading after election outcomes were effectively settled, separate from questions about combo-contract counting. Polymarket says it investigated and blocked the accounts.
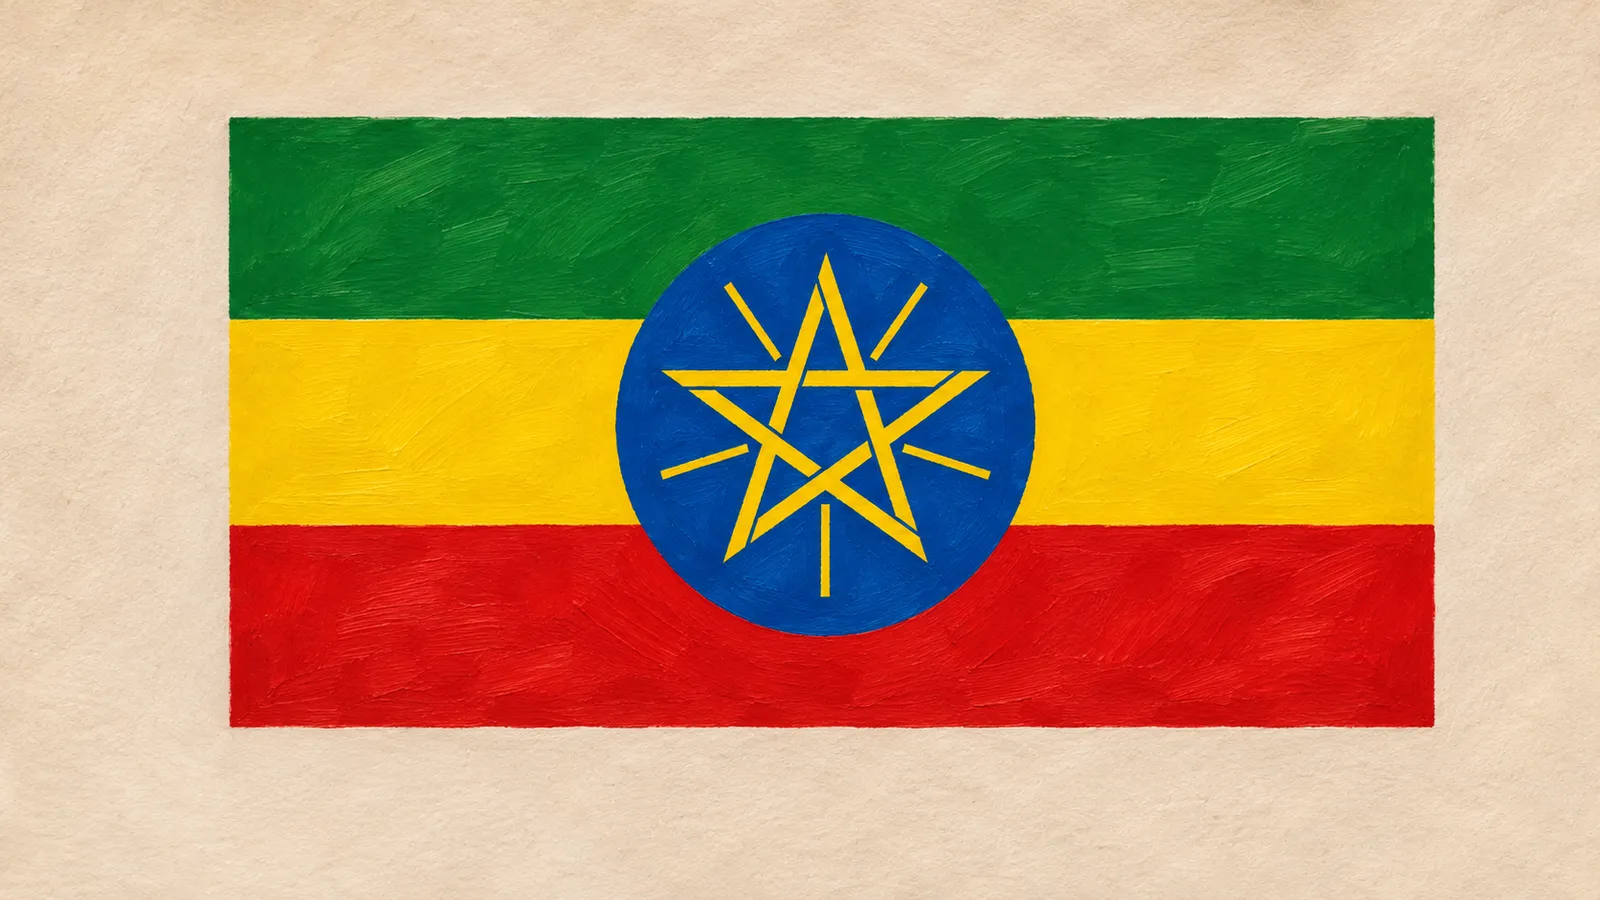
Two election markets on Polymarket’s offshore platform generated more than $600 million in trading, with repeated buying and selling continuing after the outcomes were effectively settled, according to a WIRED investigation republished by Ars Technica on 16 October. Analysis of the Ethiopian market points to suspected efforts to increase recorded activity, rather than ordinary profit-seeking. Polymarket said it investigated and blocked the accounts involved.
Prediction markets let people trade contracts tied to outcomes such as elections and sports results. The investigation follows CNBC reports on 1 and 6 October examining unusual trading and how contract-counting rules can produce large volume totals from small cash stakes. The distinction matters to investors because both Polymarket and rival Kalshi have used rising volume to support claims of popularity and their valuations.
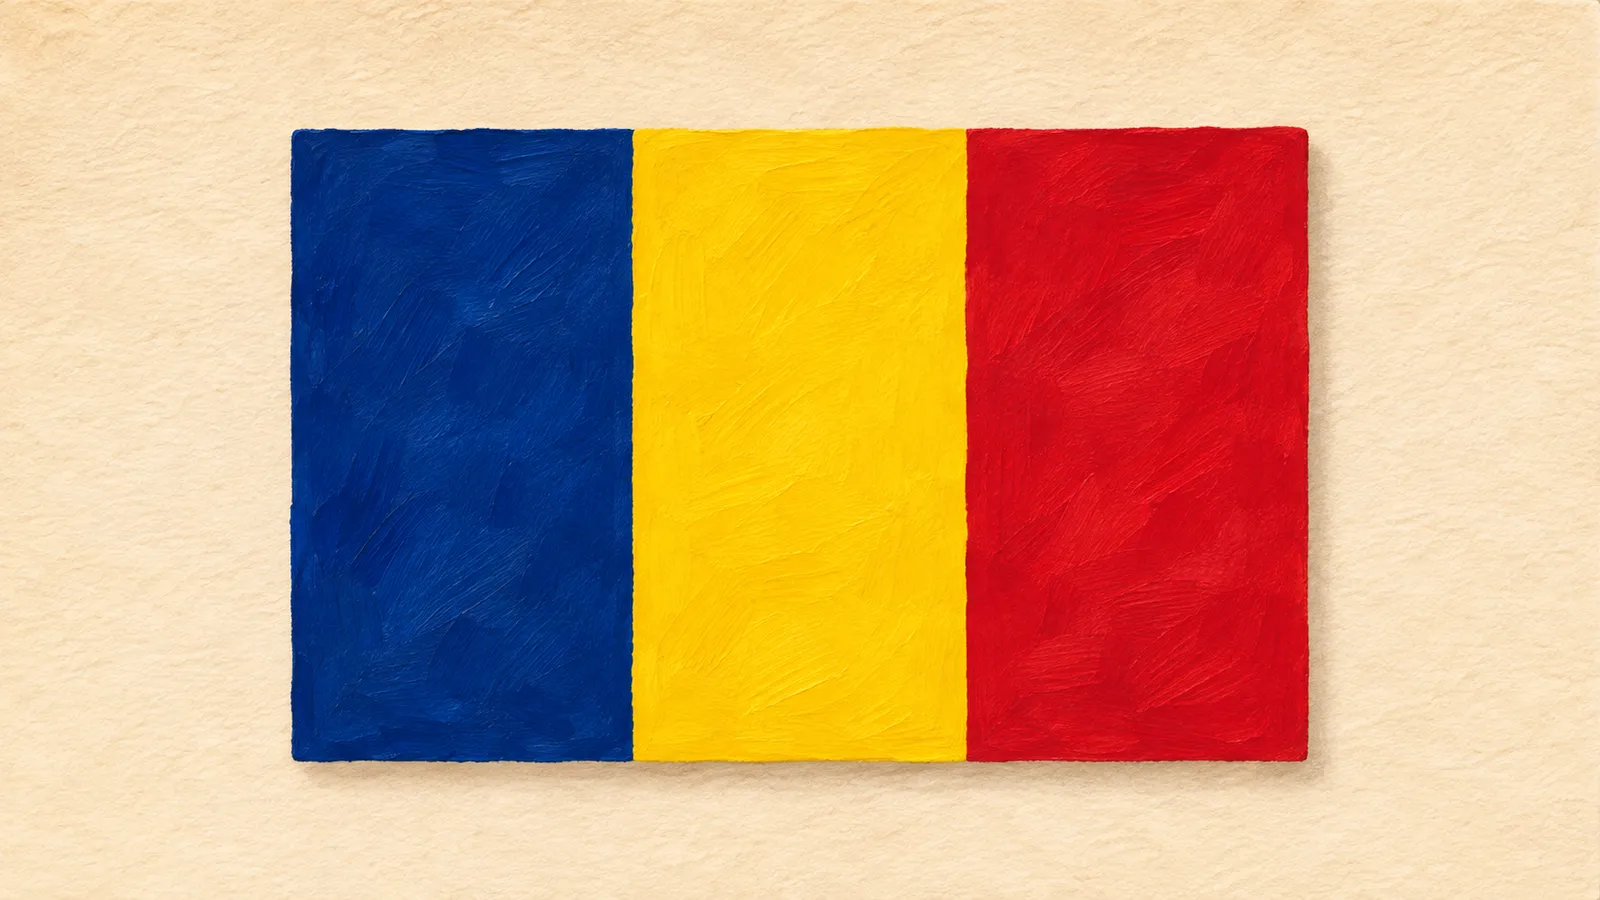
Ethiopia’s market stayed open for months after Prime Minister Abiy Ahmed’s victory was effectively assured. Its rules tied resolution—the final decision on which contracts pay—to his formal appointment and swearing-in in October. WIRED reported bursts of trading for 123 days after the election. In Romania, Polymarket kept its original 2024 election market open after the vote was cancelled over fears of foreign interference, alongside a market for the replacement election held several months later.
Markets covering HSBC, Lloyds and other banks have prompted warnings about incentives to influence outcomes and the difficulty of identifying bettors.
Prediction-market analysis firm MSR Decode examined the Ethiopian trades for WIRED. It studied more than 38,000 post-election “trade loops,” in which digital wallets bought and sold contracts to each other in quick succession. The firm found that over 98% left neither side gaining nor losing money. The median holding time before resale was nine seconds.
| Measure | Reported finding |
|---|---|
| Total market trading volume | More than $285 million |
| Volume from pairs of accounts repeatedly trading with each other, according to MSR Decode | About $284 million |
| Post-election trade loops examined | More than 38,000 |
| Loops producing no gain or loss for either side | More than 98% |
| Median contract holding time | Nine seconds |
MSR Decode judged “activity farming”—artificially increasing recorded trading volume—the most likely explanation. The firm suspects traders hoped that higher volume would benefit them if Polymarket launched a cryptocurrency token. That proposed motive is not established, and the traders’ identities remain unknown.
Barnard College economist Rajiv Sethi said a detection algorithm developed with colleagues flagged nearly all the Romanian market’s volume as suspicious; he put the share at 99.6% during certain weeks. Wash trading means repeated buying and selling that creates a false impression of activity. It is prohibited by Polymarket’s terms and banned on regulated US financial exchanges. Sethi cautioned that apparent wash trading is not always wash trading, so the patterns alone do not establish who controlled the accounts or why they traded.
Polymarket’s head of global intelligence and investigations, Shana Bautista, told WIRED that the company immediately flagged the activity, investigated and blocked the accounts from trading. Polymarket did not answer follow-up questions about why the accounts had been able to generate so much volume before it acted.
CNBC’s 1 October report had already described unusually heavy trading in unlikely outcomes on Polymarket’s international exchange, which is not overseen by US regulators. CNBC did not detect the same pattern in its September analysis of 2028 presidential-nominee contracts on Polymarket’s US exchange, which is regulated by the Commodity Futures Trading Commission (CFTC). Its Ethiopian example compared the following contracts after Ahmed’s June election victory:
| Candidate | Contract-implied probability | Trading volume |
|---|---|---|
| Abiy Ahmed | 98% | About $170,000 |
| Gedion Timothewos | Below 3% for months | Almost $56 million |
That report said settlement depended on the elected government’s official swearing-in, then scheduled for 5 October. Polymarket’s revenue and analytics head, Kyle Gesuelli, attributed low-probability trading to highly active traders using software and algorithms to exploit small pricing errors. He said such traders were more common internationally, while casual individual traders dominated the US exchange. MSR Decode’s later analysis judged profit-seeking an unlikely explanation for the Ethiopian loops it examined.
CNBC also reported earlier Columbia University research classifying some international trading patterns as indicative of wash trading. Lead author Allen Sirolly said that study’s measure had fallen to a negligible level by April 2026, though he remained concerned about low-probability contracts. Polymarket said expanded surveillance and fees had reduced opportunities for manipulation. Both Polymarket and Kalshi denied wash trading and artificial activity in CNBC’s 1 October report.
The repeated transactions examined by WIRED are separate from the accounting issue CNBC explained on 6 October. Combos bundle event contracts and pay only if every outcome wins, like a parlay in sports betting. According to Dune data cited by CNBC, combos represented 58% of Kalshi’s September trading volume but fewer than 13% of transactions.
CNBC attributed the counting method to CFTC requirements. A standard contract paying either $0 or $1 records $1 of notional volume—a measure based on contract value—regardless of the buyer’s price. The money committed by both sides makes up that dollar. Combos can have much larger payouts, so pennies paid by a buyer can register as potentially thousands of dollars in volume when market makers take the opposite side. Market makers offer to buy and sell so others can trade.
| Trade or contract measured | Average cash committed |
|---|---|
| Single-contract trade | Less than 47 cents per trade |
| Combo contract | About 9 cents per contract |
Sportsbook “handle” measures dollars wagered, whereas prediction-market volume counts both sides of a trade. Bernstein analyst Ian Moore told CNBC that some investors compare those different totals to argue that prediction markets have exceeded sports betting’s scale. Kalshi said its notional totals do not overstate activity; spokesperson Jack Such said people interested in other measurements could use other metrics.
Some observers favor taker volume: trades that accept orders already supplied by market makers, rather than supply new orders. Gesuelli said Polymarket favors tracking taker purchases of “yes” on combos to understand demand for all the combined outcomes occurring. CNBC disclosed a commercial relationship with Kalshi involving customer acquisition and a minority investment.
The earlier scrutiny also covered cryptocurrency-linked perpetual futures, contracts without a fixed expiry date. CNBC found that nearly half the dollar volume in Kalshi’s ether perpetuals on 20 September came from trades sized between $5,495 and $5,505. Kalshi said hundreds of users participated and that it monitors self-trading—trading against one’s own orders or accounts—and collusion. Experts CNBC interviewed broadly agreed the trades likely were not wash trading.
Kalshi attributed the pattern to arbitrage, or profiting from price differences: when cryptocurrency prices move elsewhere, traders can take an outdated market-maker quote on Kalshi. Critics pointed to market-maker payments and Kalshi’s trading-fee waiver through the end of 2026. Sethi argued that fee rebates make these profits consistently possible. Kalshi defended the incentives as necessary to build liquidity—the availability of trades—in a new market. In WIRED’s later report, Sethi again agreed that wash-trading allegations against Kalshi were unfounded and pointed instead to its incentives.
Volume counts trading over a period; open interest measures positions that remain open. Rapid turnover can therefore produce high volume without a similarly large amount of outstanding positions. A snapshot in CNBC’s 1 October report showed much higher volume relative to open interest on Kalshi than on two offshore exchanges:
| Exchange | Perpetual futures contract | 24-hour volume as a multiple of open interest |
|---|---|---|
| Kalshi | Bitcoin | About 42 times |
| Kalshi | Ether | About 66 times |
| Polymarket | Ether | About three-quarters |
| Hyperliquid | Ether | About one-third |
The ratios compare 24-hour volume with open interest at the snapshot. Experts interviewed by CNBC said the rapid turnover undermined the success of Kalshi’s incentives in building liquidity, and questioned whether traders mainly sought incentive payments. The Polymarket and Hyperliquid perpetual futures exchanges are unavailable in the US. CNBC also noted that traditional bitcoin futures on CME, a regulated US exchange, typically have volume below open interest.
Such disputed the offshore comparison. He cited lower leverage, which allows positions larger than the funds committed: Kalshi permits up to 4.9 times leverage on ether perpetuals, versus Hyperliquid’s 25 times. He also cited infrastructure and US rules, saying Kalshi does not let market makers revise quotes when prices change and cannot reward users simply for keeping capital on the platform. Such said Kalshi had “zero concerns” about its volume-to-liquidity ratio.
Tamika Bent, a partner at law firm K&L Gates, told CNBC that unusual patterns alone do not establish exchange misconduct. She said designated contract markets, the regulated exchange category, must monitor conditions, prices and volumes in real time for abnormalities. Observers would also expect them to investigate unusual volume and signs of market disruption.
Ulm University finance professor Andre Guettler warned in a working paper that, if a material share of perpetual futures volume is manufactured, headline volume and growth could overstate demand supporting a valuation. That was a conditional warning, not a finding that the disputed trades were manufactured. WIRED put Polymarket’s latest valuation at an estimated $21 billion after a funding round exceeding $1 billion.
The Wall Street Journal previously reported that the CFTC was examining trades in Kalshi’s ether perpetual contract; CNBC said it could not independently verify that account, and the regulator said it does not confirm or deny investigation matters. Asked about the Ethiopian and Romanian election trades, the CFTC declined to say whether it was looking into them. Whether those trades will lead to regulatory action remains unresolved.
3 min
A $1.75 billion round for the autonomous-vessel developer dominates a nearly $3 billion total that also spans robotics, electric shipping and ocean energy.
3 min
Its forecast has more jobs created than displaced, but many workers would need new skills or qualifications—and most growing jobs cannot be done remotely.
2 min